How we picked the top medical billing companies
A company made this list only if its own website publishes a numeric billing rate, or the base its fee is taken on, that a small practice can check before calling. We read each company's own pricing, FAQ or small-practice page on November 4, 2026 and recorded only what that page states. Where a page is silent on a term, the table says "not stated on the page": we did not find it there, which does not mean the company lacks it.
The list is alphabetical. It is not ranked, scored or rated, because published terms cannot show which company will collect more for your practice, and we did not test any company's service.
Disclosure: ClaimPillar Medical Billing publishes this page and is one of the ten companies. Our row passes the same published-terms test as every other row, using our own published rate card.
The five criteria every company is compared on
- The published rate, and what it is a percentage of.
- Any setup or onboarding fee.
- Any monthly minimum or floor.
- Contract length, notice period, and what happens to your claims and files when you leave.
- Any guarantee, and whether its terms are published.
Companies that publish neither a rate nor a fee base were left out. That excludes many large and well-known billing companies; it says nothing about their service, only that a reader cannot check their price from outside. For vendors that sell outsourcing without a published rate, compare medical billing outsourcing companies on the same five criteria.
Top 10 medical billing companies at a glance (alphabetical, not ranked)
Each row condenses the company's own words. A "starting at" or "from" rate is that company's lowest rate, not your quote: BillingParadise, for example, says its rate depends on specialty, claim volume and payer mix. The pages we read: 247 Medical Billing Services, ClaimPillar, Go Medical Billing, MedStates, NEXACC, Raven Health, Swift Medical Billing, TheraThink and VG Soft Co.
| Company | Published rate (as stated) | Rate is a percentage of | Setup fee | Monthly minimum | Contract and exit | Source, retrieved |
|---|---|---|---|---|---|---|
| 247 Medical Billing Services | 4–8%; "no collection, no fee" | What it collects (collections, not charges) | Not stated on the page | Not stated on the page | "No long-term lock-in"; notice period not stated | 247medicalbillingservices.com pricing page, 2026-11-04 |
| BillingParadise | From 2.99%, by specialty, claim volume and payer mix | Collections | None (no setup or onboarding fee) | Not stated on the page | Month-to-month; no long-term contract | billingparadise.com pricing page, 2026-11-04 |
| ClaimPillar (publisher of this page) | 5.0%–8.5% by specialty and practice size | Insurance payments; 0% of patient payments | $0 | $400, starting with your 4th monthly invoice | Month to month. Leave with 30 days' written notice. No termination fee. | claimpillar.com/pricing/, 2026-11-04 |
| Go Medical Billing | Starting at 2.49% | Net collections | None | None ("no monthly minimums") | Either party may end it with 30 days' notice | gomedicalbilling.com small-practice page, 2026-11-04 |
| MedStates | Starting at 2.99% for qualifying practices | Payments collected from insurance companies (percentage model) | $0 setup and onboarding | Not stated on the page | No long-term contracts | medstates.com fee page, 2026-11-04 |
| NEXACC | 5–6%; behavioral health at 5% | What it collects for you, not charges | Not stated on the page | $950 a month floor: you pay the percentage or $950, whichever is higher | 30 days' notice; files returned within 5 business days | nexacc.com cost article, 2026-11-04 |
| Raven Health (ABA) | Concierge 5%; Concierge Pro 7% | Monthly claims paid | Not listed for Concierge plans ($500 implementation fee on its software plans) | $1,000 on Concierge plans | Annual contract | ravenhealth.com pricing page, 2026-11-04 |
| Swift Medical Billing | 4–7%, by specialty and claim volume | Monthly net collections | None | Not stated (no minimum practice size or claim volume) | Not stated on the page | swiftmds.com small-practice page, 2026-11-04 |
| TheraThink (mental health) | A percentage; the figure is not stated on its FAQ | The allowed amount (insurance payment plus patient responsibility), on paid claims only | No start-up fee; a $35 monthly clearinghouse fee per tax ID and rendering NPI | No minimum number of claims | Month-by-month | therathink.com FAQ, 2026-11-04 |
| VG Soft Co (ABA) | 3% (A/R management) or 6% (full-service RCM) | Collected revenue | $0 | Not stated on the page | Month-to-month; cancel with 30 days' written notice | vgsoft.co ABA pricing page, 2026-11-04 |
Fees compared: % of insurance payments vs % of all collections
The percentage is only half of a billing quote; the other half is what it is a percentage of. The ten companies above use four different bases:
- Collections or net collections: Go Medical Billing, BillingParadise, Swift Medical Billing, 247 Medical Billing Services, NEXACC and VG Soft Co. VG Soft Co says its percentage applies to dollars from payers and patients; the other pages we read do not say whether copays and other patient payments count toward collections, so ask.
- Insurance payments: MedStates describes its percentage model as a share of payments collected from insurance companies, and we charge 0% of patient payments.
- Allowed amount: TheraThink's FAQ says it charges on the allowed amount, which it defines as the patient responsibility plus the insurance payment, and only on paid claims it completed.
- Claims paid: Raven Health prices its Concierge plans on monthly claims paid.
Worked example: the same 6% on two fee bases
Illustrative example, not client data. Take a practice with $30,000 of insurance payments and $6,000 of patient payments in a busy month, and $8,000 and $1,600 in a slow one. Three hypothetical quotes all say "6%":
In the busy month, the all-collections quote costs $360 more than the insurance-only quote: $4,320 a year if every month looked the same. In the slow month, the $1,000 minimum turns a 6% quote into 12.5% of insurance payments. The allowed-amount base behaves like all collections claim by claim: on a visit with a $120 allowed amount where the plan pays $90 and the patient owes $30, 6% of the allowed amount is $7.20, while 6% of the insurance payment is $5.40.
Our own example, on our rate card: Example: 3 therapists with $30,000 of insurance payments in a month pay 7.5%, or $2,250. That month's cap would be $2,700. The same practice in a slow month: $4,000 of insurance payments at 7.5% is $300. Invoices 1–3 charge $300; from invoice 4 the $400 minimum applies, even though that month's 9.0% cap is $360.
| Hypothetical quote | Busy month: $30,000 insurance + $6,000 patient payments | Slow month: $8,000 insurance + $1,600 patient payments |
|---|---|---|
| 6% of all collections | $2,160 | $576 |
| 6% of insurance payments only | $1,800 | $480 |
| 6% of insurance payments, $1,000 monthly minimum | $1,800 | $1,000 (12.5% of insurance payments) |
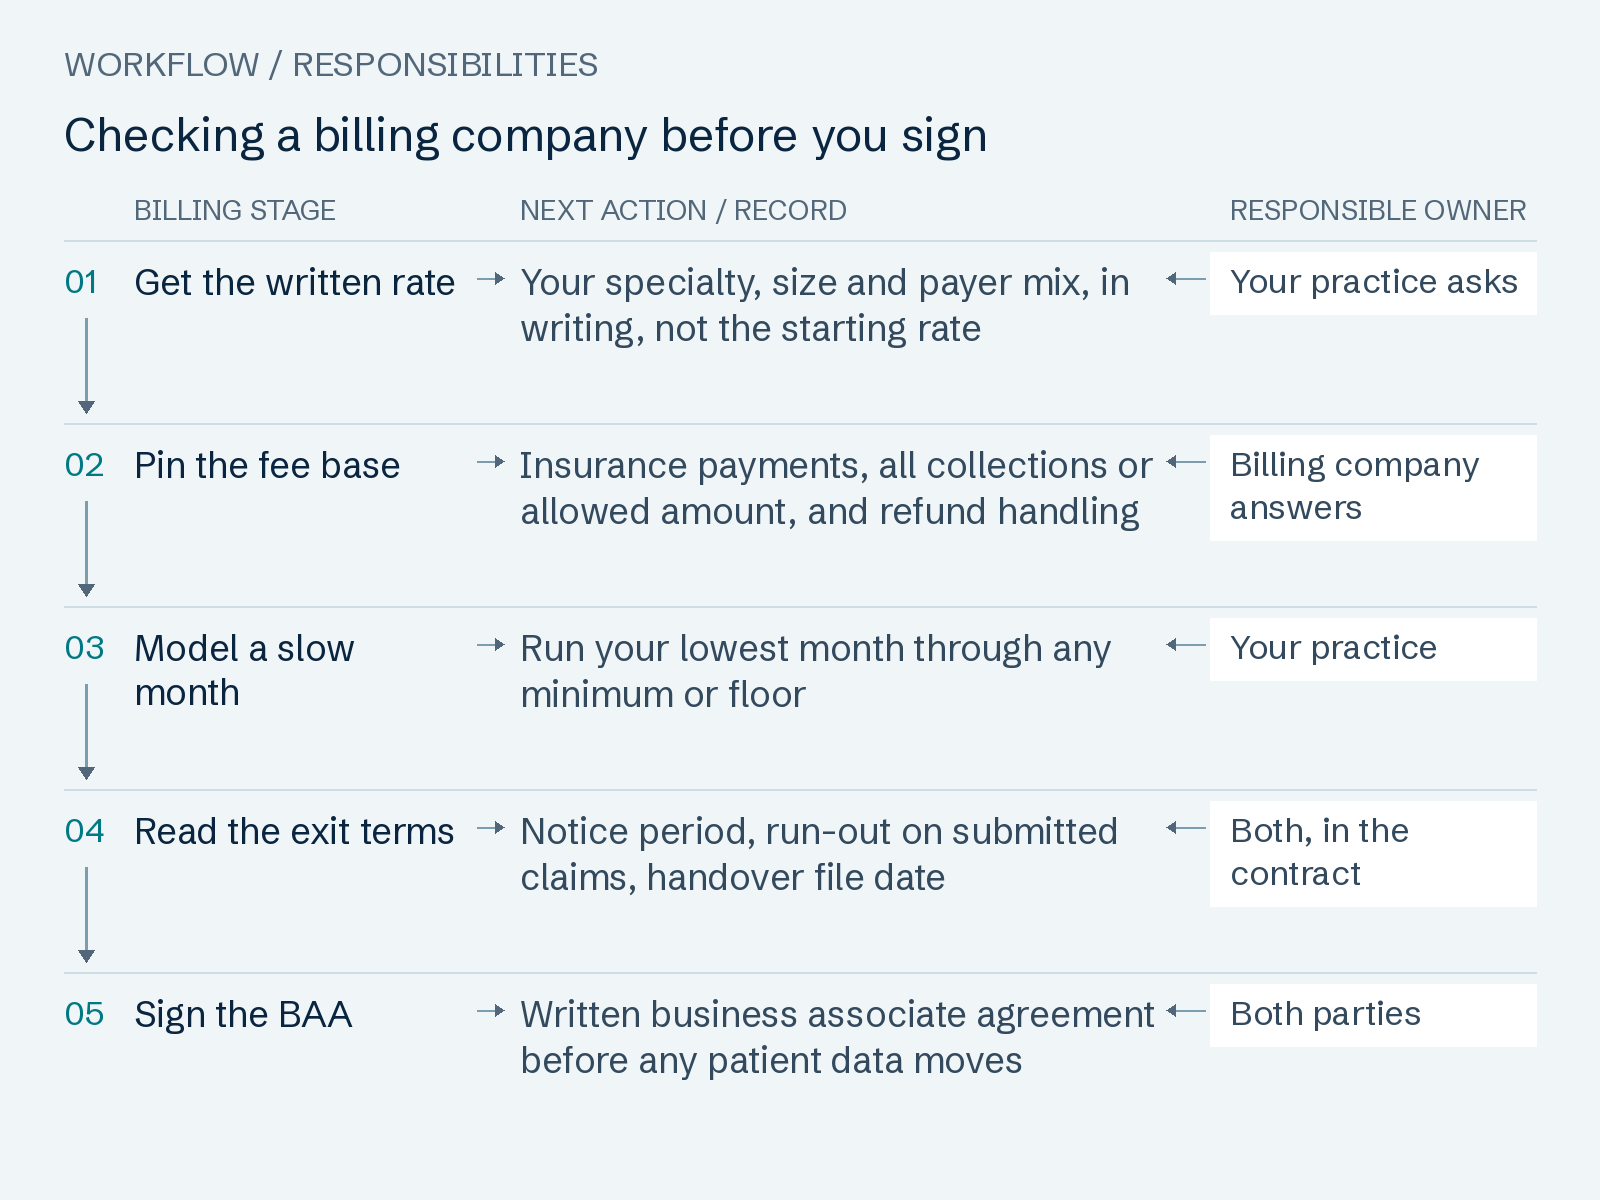
Read the workflow as text
- Get the written rate — Your specialty, size and payer mix, in writing, not the starting rate Owner: Your practice asks.
- Pin the fee base — Insurance payments, all collections or allowed amount, and refund handling Owner: Billing company answers.
- Model a slow month — Run your lowest month through any minimum or floor Owner: Your practice.
- Read the exit terms — Notice period, run-out on submitted claims, handover file date Owner: Both, in the contract.
- Sign the BAA — Written business associate agreement before any patient data moves Owner: Both parties.
Minimums, setup fees and exit terms
Seven of the ten companies publish no setup fee: BillingParadise, Go Medical Billing, MedStates, Swift Medical Billing, TheraThink, VG Soft Co and us ($0). Raven Health lists a $500 implementation fee on its software-only plans and none on its Concierge billing plans. The 247 Medical Billing Services and NEXACC pages we read do not mention setup fees.
Why a minimum matters more to a small practice
A monthly minimum or floor costs nothing in a busy month and sets your effective rate in a slow one. Divide the minimum by your lowest month of insurance payments from the past year: that is the rate you pay in that month. Besides ours, two companies publish one: NEXACC charges the percentage or $950, whichever is higher, and Raven Health has a $1,000 minimum on its Concierge plans. Go Medical Billing says it has no monthly minimums, and TheraThink says it needs no minimum number of claims. Ours: Invoices 1–3: only percentage fees on that month's insurance payments, plus any statements or add-ons you order; the $400 minimum starts with invoice 4. Percentage fees and mailed statements are capped at 9.0% of that month's insurance payments; the $400 minimum still applies from invoice 4.
What happens when you leave
Exit terms decide whether a bad fit costs you one month or one year. Go Medical Billing lets either party end the agreement with 30 days' notice. NEXACC asks for 30 days' notice and says your files come back within 5 business days. BillingParadise and TheraThink describe month-to-month terms, VG Soft Co is month-to-month with 30 days' written notice, and MedStates says it requires no long-term contract. Raven Health's plans run on an annual contract. 247 Medical Billing Services says there is no long-term lock-in but does not state a notice period on its pricing page, and Swift Medical Billing's small-practice page does not state contract terms. Ours: Month to month. Leave with 30 days' written notice. No termination fee. Notice by email; optional run-out covers claims we submitted before your exit date, at your plan rate; handover file within 10 business days of exit.
Whoever you choose, get three exit items in writing: who works the claims already submitted after you leave, what the handover file contains, and the date you receive it. The switch itself is where claims slip, so plan it with a guide to switching billing companies without losing A/R.
Guarantees: what each company actually promises
A performance percentage is not a guarantee unless the company says what it pays or credits when it misses. Several pages state a clean-claim or paid-claim figure; only a contract can tell you the remedy, the cap and the exclusions. No billing company can make a payer approve a claim.
Our two guarantees, with their full terms:
- On-Our-Watch Guarantee: If a claim misses a filing, corrected-claim or appeal deadline while it is on our watch, we pay you what it would have paid. Terms: Claims we get complete 10+ business days before the deadline; contracted rate less any copay you collected, paid automatically within 30 days of final denial; capped $10,000/month; your holds excluded.
- Clock-or-Credit Guarantee: From go-live, every new claim goes out within 1 business day of complete charge data, and every denial is worked within 2 business days of posting — or $25 comes off your invoice for each late one. Terms: Mon–Fri ET business days by your system's timestamps; worked: resubmitted, appealed or returned with the fix; auto-credited; capped at monthly fee; clearinghouse outages excluded.
Both apply only on the terms above.
| Company | What its page states | A guarantee with published terms? |
|---|---|---|
| 247 Medical Billing Services | A "98% Clean Claims" figure | No; stated as a figure |
| BillingParadise | "95% Guaranteed" for first-pass claim payment, in its pricing-page comparison table | Called guaranteed; the remedy if missed is not stated on that page |
| ClaimPillar | On-Our-Watch Guarantee and Clock-or-Credit Guarantee | Yes; terms above |
| Go Medical Billing | A 92%+ clean claim rate | No; stated as a figure |
| MedStates | No guarantee found on its fee page | Not applicable |
| NEXACC | Files returned within 5 business days after you leave | An exit commitment, not a performance guarantee |
| Raven Health | A customer story headlined "98% of Claims Paid" | No; one client's result, not a guarantee |
| Swift Medical Billing | No guarantee found on its small-practice page | Not applicable |
| TheraThink | Charges only for paid claims it has completed | A fee condition, not a guarantee |
| VG Soft Co | "95% of Your ABA Claims Paid" | No; stated as a figure |
Best fit by specialty: therapy, ABA, behavioral health, primary care, specialists
Specialty fit matters as much as price, because each specialty denies claims for different reasons. The verdicts below rest only on what each company publishes; check each one against your own payer mix.
Therapy and behavioral health
TheraThink builds its service around mental health professionals and charges on the allowed amount; choose it if you want a therapy-only biller and accept that fee base. NEXACC publishes a 5% behavioral health rate with a $950 floor; it suits a group whose slowest month still clears the floor comfortably. Our Mental & behavioral health rates run from 7.0% for 6–15 clinicians to 8.0% for a solo clinician, and our PT, OT, speech & chiropractic rates from 6.5% to 7.5%. More detail on mental health billing services.
ABA
Two ABA-only options publish rates. VG Soft Co's 3% tier is for practices that keep their own billing staff and want A/R follow-up handled; its 6% tier runs the whole cycle. Raven Health bundles billing with its ABA practice software at 5% or 7% of claims paid, with a $1,000 Concierge minimum and an annual contract; choose it if you want one vendor for software and billing. Our ABA therapy rates run from 7.5% to 8.5%, by size band. See ABA therapy billing services.
Primary care and specialists
Go Medical Billing, BillingParadise, MedStates and Swift Medical Billing sell to practices across specialties, and BillingParadise and Swift Medical Billing price by specialty. Go Medical Billing writes its small-practice offer for 1-to-5 provider practices. MedStates and 247 Medical Billing Services also offer flat-fee or hourly models, which can suit a practice with steady claim volume. Our Primary care, pediatrics & urgent care rates run from 5.5% to 6.5%, and Specialist physician groups from 5.0% to 6.0%.
Every ClaimPillar rate in this section carries the same terms: Invoices 1–3: only percentage fees on that month's insurance payments, plus any statements or add-ons you order. Percentage fees and mailed statements are capped at 9.0% of that month's insurance payments; from invoice 4, the $400 minimum applies even in a month when the cap comes to less.
How to check a billing company before you sign
Seven checks separate a fair contract from an expensive one. Each takes one question or one document.
- Get the rate for your specialty, size and payer mix in writing. A "starting at" rate is the company's lowest, not yours.
- Ask what the percentage is taken on: insurance payments, all collections or the allowed amount, and whether payer recoupments and refunds come back out of the fee.
- Run your slowest month from the past year through any minimum or floor.
- Confirm where payer payments land. Medicare pays a billing agent directly only if, among other conditions, the agent's compensation is not related in any way to the dollar amounts billed or collected (42 CFR 424.73). A company paid a percentage should leave those payments going to your practice's account.
- Sign a business associate agreement before any patient data moves. HIPAA counts a company that does billing for a provider as a business associate (45 CFR 160.103) and requires its assurances to be documented in a written contract (45 CFR 164.502(e)).
- Read the exit clause: notice period, run-out on claims already submitted, and when your files come back.
- Ask what each guarantee pays, its cap and its exclusions.
For the full question list, with what a good answer looks like, use the checklist for choosing a medical billing company.
Where ClaimPillar fits, and when another company fits better
We do not rank ourselves. On the five criteria, our published terms are these:
- Rate and fee base: 5.0%–8.5% of insurance payments, by specialty and practice size, and 0% of patient payments. Not in the fee base: patient payments, copays, capitation, incentive or grant payments, and payments on claims we never submitted or worked.
- Setup and minimum: $0 setup. Invoices 1–3: only percentage fees on that month's insurance payments, plus any statements or add-ons you order. Percentage fees and mailed statements are capped at 9.0% of that month's insurance payments; from invoice 4, the $400 minimum applies even in a month when the cap comes to less.
- Exit: Month to month. Leave with 30 days' written notice. No termination fee. Notice by email; optional run-out covers claims we submitted before your exit date, at your plan rate; handover file within 10 business days of exit.
- Guarantees: the On-Our-Watch Guarantee and the Clock-or-Credit Guarantee, on the terms in the guarantees section above.
We publish client results only with written permission. Until we have them, judge us by the guarantees and the free Deadline Map.
When another company may fit better
- Your payer mix is simple and price per dollar collected matters most: a confirmed starting rate of 2.49% or 2.99% from the companies above may cost less than our card.
- You run ABA and want billing inside your clinical software: Raven Health sells both together.
- You keep an in-house biller and only need aging claims worked: VG Soft Co's 3% tier is built for that, and our A/R Recovery covers inherited claims at 15%. Fee only on insurance payments posting after our logged action; patient payments 0%; full-service clients stay under the 9.0% fee cap.
- You want credentialing, eligibility and authorizations run by the same team: compare revenue cycle management companies as well.
If our terms fit, start with medical billing services for small practices, or read how our medical billing outsourcing works for any size of practice. See the full rate card.
Common questions
- What is the best medical billing company for a small practice?
- No single company is best for every small practice. Shortlist companies that bill your specialty, then compare their published rate, what that rate is taken on, any monthly minimum, the exit terms and any guarantee with its terms. The comparison table does that for ten companies that publish their pricing terms, including us.
- What do top medical billing companies charge?
- Among the ten companies on this page, published figures run from a 2.49% starting rate (Go Medical Billing) to ranges of 4–7% (Swift Medical Billing) and 4–8% (247 Medical Billing Services), with ABA plans at 3% to 7%. Our card runs 5.0%–8.5% of insurance payments; Invoices 1–3: only percentage fees on that month's insurance payments, plus any statements or add-ons you order. Percentage fees and mailed statements are capped at 9.0% of that month's insurance payments; from invoice 4, the $400 minimum applies even in a month when the cap comes to less.
- Do billing companies charge on patient payments?
- Some do. A fee on the allowed amount, as TheraThink describes its fee, includes the patient's share, and a fee on "collections" may include copays unless the contract says otherwise: VG Soft Co, for one, applies its percentage to payments from payers and patients. MedStates describes its percentage model as a share of insurance payments, and we charge 0% of patient payments. The worked example shows what the difference costs.
- What should a billing contract include?
- The rate and the exact fee base, any setup fee, the monthly minimum, the notice period, who works claims already submitted after you leave, the handover file and its date, each guarantee's remedy, cap and exclusions, and a business associate agreement, which HIPAA requires in writing (45 CFR 164.502(e)).
- Why does this page have no rankings or star ratings?
- Published terms show what a company charges and promises, not how well it bills your claims, and we did not test any company's service. Ranking competitors would also be self-serving, because ClaimPillar publishes this page and is on the list. The companies are listed alphabetically instead.
- How current are the prices on this page?
- Every competitor fact was read from that company's own page on November 4, 2026, and each row names its source. Billing companies change prices without notice, so confirm the rate and terms in writing before you sign. Our own terms come from our pricing page.
Sources and review
Page revised November 4, 2026 · Review contact: Hyder Shah (inquiries@claimpillar.com). Competitor terms come from each company's own page, retrieved November 4, 2026; prices change, so confirm them in writing before you sign.
- 247 Medical Billing Services: pricing (retrieved 2026-11-04)
- BillingParadise: medical billing pricing (retrieved 2026-11-04)
- Go Medical Billing: medical billing for small practices (retrieved 2026-11-04)
- MedStates: medical billing services pricing models (retrieved 2026-11-04)
- NEXACC: how much does medical billing cost? (retrieved 2026-11-04)
- Raven Health: ABA billing software pricing and plans (retrieved 2026-11-04)
- Swift Medical Billing: medical billing services for small practices (retrieved 2026-11-04)
- TheraThink: FAQ on its mental health insurance billing service (retrieved 2026-11-04)
- VG Soft Co: ABA billing service pricing (retrieved 2026-11-04)
- 42 CFR 424.73: payment to an agent (Medicare, eCFR, retrieved 2026-11-04)
- 45 CFR 160.103: definition of business associate (HIPAA, eCFR, retrieved 2026-11-04)
- 45 CFR 164.502(e): disclosures to business associates (HIPAA, eCFR, retrieved 2026-11-04)